The AML/CTF Act 2006 (Cth) captures services, not professions. Six sectors came under the main obligations on 1 July 2026: accountants, legal practitioners, conveyancers, real estate agents, dealers in precious metals and stones, and trust and company service providers. Within each sector the same test applies: whether the work you do matches a service the Act lists as designated.
A designated service is a service the Act lists as one the regime regulates. The lists sit in the tables to s6 of the Act. Table 6, inserted by s 6(5B), covers the professional services: the conveyancing, company and trust work that captures the professions. Real estate agency work sits in Table 5, and precious metals and stones in Table 2. Provide one of those services in the course of carrying on a business and you become a reporting entity, the person the Act holds responsible for enrolment, an AML/CTF program (the documented set of policies and procedures each reporting entity must have), customer due diligence and reporting. Enrolment opened 31 March 2026, and obligations started on 1 July 2026.
The rest of this page maps each sector to the services that capture it. Find your profession, find your work, and check it against the table below.
The six sectors and the services that capture them
Each row names the services that capture a sector and where those services sit in the Act. The item numbers in the tables matter when you scope your program, and they are flagged for verification at the end of this page.
| Sector | Services that capture you | Where the service sits in the Act |
|---|---|---|
| Legal practitioners | Conveyancing; buying or selling a company or trust; holding client money for a transaction; company and trust work | Table 6, s 6(5B), items 1, 2, 3 (subject to s 6(5C)) and 6, and any other Table 6 item you provide |
| Accountants | Company and trust work; buying or selling a company or trust; arranging equity or debt financing for a company or trust; holding or managing a client’s money as part of their transaction | Table 6, s 6(5B), items 2, 3, 4 and 6 (item 3 subject to s 6(5C)), and any other Table 6 item you provide |
| Conveyancers | Assisting in a conveyance | Table 6, s 6(5B), item 1 |
| Real estate agents | Brokering the sale, purchase or transfer of real estate; selling or transferring real estate | Table 5 (real estate services), not Table 6 |
| Trust and company service providers | Selling shelf companies; creating or restructuring companies and trusts; acting as or arranging a trustee, director, secretary or nominee shareholder; providing a registered office or principal place of business address | Table 6, s 6(5B), items 5 to 9 |
| Dealers in precious metals and stones | Buying or selling precious metals, stones or products (including jewellery) for $10,000 or more in physical currency or virtual assets; bullion dealing as a business | Table 2, items 2 and 1 |
If any service in a row describes work you do, that service is captured. You do not need to provide all of them, and you do not need to provide the service often. One conveyance a year makes the service captured; the rest of your work is a separate question.
Legal practitioners: conveyancing and company work
Two services anchor the legal row: assisting in a conveyance (item 1), and creating or restructuring a company or trust (item 6). Helping a client buy or sell a company or trust (item 2) and holding client money for a transaction (item 3, subject to s 6(5C)) are also common. Do any of them and the main obligations apply to that work from 1 July 2026, whether you are a sole practitioner or a national firm. The full list of legal practice services sits in Table 6 of the Act.
Accountants: company, trust and client money work
The accounting services cover company and trust work: creating or restructuring a company or trust for a client (Table 6 item 6), helping a client buy or sell a company or other body corporate, or a legal arrangement such as a trust (item 2), and helping a client organise, plan or carry out equity or debt financing for a company or trust, including one not yet formed (item 4). Receiving, holding or managing a client’s money is captured only when it is part of assisting the client in the planning or execution of a transaction, or acting for them in one (Table 6 item 3), and not in the circumstances s 6(5C) excludes, such as money held as payment for your own fees. Table 6 is not limited by profession, so an accountant who sells shelf companies, acts as a director or nominee for a client, or provides a registered office address is captured for that work too (items 5, 7, 8 and 9). Work that matches no item in the tables to s6 does not capture you. Routine bookkeeping, tax returns, BAS work and preparing financial statements for an existing business, for example, are not designated services on their own. The capture follows the listed service, not your professional registration.
Conveyancers: the transfer of real property
Conveyancers are captured through the conveyancing service itself: assisting in a conveyance, which means preparing, executing and settling the transfer of real property for a buyer or seller. The service is defined by the work, not by the licence you hold. You are captured whether you call yourself a conveyancer or a law firm.
Real estate agents: sales, purchases and deposits
The real estate services are brokering the sale, purchase or transfer of real estate for a buyer, seller, transferee or transferor (Table 5 item 1), and selling or transferring real estate in the course of a business selling real estate where no independent agent brokers the sale (item 2). For a brokered sale, both the seller and the buyer are customers of the service. Holding the deposit while you broker the sale is part of the brokering service rather than a separate designated service, because the money-handling item in Table 6 does not apply where the service is another designated service (s 6(5C)(e)).
Trust and company service providers: formation, trusteeship and nominees
The trust and company services cover selling or transferring shelf companies (Table 6 item 5), creating and restructuring companies and trusts (item 6), acting as or arranging for someone to act as a director, company secretary, partner or trustee, or as a power of attorney of a company or trust, on a client’s behalf (item 7) or as a nominee shareholder (item 8), and providing a registered office or principal place of business address (item 9). Much of this work was already performed by accountants and lawyers; the reforms capture it as a service in its own right. You are captured for that work whether you are a trust company, an accountant or a law firm.
Dealers in precious metals and stones: the trade itself
The dealers’ service is set by the Act. Buying or selling precious metal, precious stones or precious products in the course of a business is a designated service where the purchase involves $10,000 or more in physical currency or virtual assets, counting transactions that are linked or appear to be linked (Table 2 item 2). Precious products include jewellery, watches, other objects of personal adornment and goldsmiths’ or silversmiths’ wares that contain precious metal or stones (s 5A(6)). Sales paid by card or bank transfer do not count towards the threshold. Buying or selling bullion as part of a bullion-dealing business is captured with no cash threshold (item 1).
Each table in s6 names the customer of the designated service: for brokering a property sale, both the seller and the buyer; for most professional services, the person you act for. That customer is who you identify and verify, and who you report on if a suspicion forms.
Two consequences follow from the service-based shape. The first is scoping: your practice can be captured for one line of work and outside for another, so your list of services is your first compliance document. The second is the program: the AML/CTF program you build has to cover the services you actually provide, not your profession’s whole range.
What catches people out
Occasional provision still captures you. The Act sets no minimum volume and no frequency test. If you provide a designated service, you are a reporting entity for it, whether you do it daily or once a year. If you assume a one-off transaction sits outside the regime, you still carry the full set of obligations for that service: enrolment, a program, verification of the customer, and reporting if a suspicion forms. Get this wrong and you operate a captured service with no program behind it, and every file you touch in that service is outside the regime’s controls.
Part of the practice can be in scope while the rest is not. Your conveyancing work can be captured while your commercial litigation sits outside. Your company and trust work can be captured while other lines of work do not appear in the tables at all. If you decide capture at firm level, you get one of two failures: you treat everything as captured and build compliance load you do not need, or you treat nothing as captured and miss the service that is in scope. Run the analysis service by service, and write the result down, because enrolment and the program both depend on it.
The court-order exclusion is narrow, and it needs evidence. Some services fall outside the tables where the transaction results from a court order. The exclusion attaches to that transaction, not to the customer and not to the service generally. A customer who was once on the receiving end of a court-ordered transaction is still a customer for every other service they ask you to provide. Treat the exclusion as a standing status and you leave captured transactions outside the regime, with no verification and no reporting. Treat the service as captured and record the court order on the file before treating anything as excluded.
What is still unsettled
How the new services apply in practice is still settling. The AML/CTF Rules (2025) and AUSTRAC’s sector guidance are working through the detail: what counts as providing a particular service, where the edges of a service sit, and how the new items interact with services that were already regulated. The table and item numbering in s6 is worth confirming against the current version of the Act before you rely on it. The trigger itself is not unsettled. If you provide a listed service, you are a reporting entity for it (from 31 March 2026 at the earliest), and the main obligations apply from 1 July 2026 or, if later, from when you start. What is settling is how precisely you can scope the edges. Write your scope now, version it, and expect to revise it.
Where to start
If you have not done this yet, start here:
- List every service you provide: write down what the firm actually does, line by line, not by profession. Match each line against this page’s table and the tables in the Act. Where a line matches, that service is captured. Where it does not, note why, so your scope decision is recorded.
- Enrol the reporting entity: enrolment with AUSTRAC opened 31 March 2026, ahead of the 1 July 2026 commencement. The enrolment guide covers who has to enrol and what the form asks for.
- Build the program around the services you found: your AML/CTF program has to reflect the services you actually provide, which is why step one comes first. The program guide sets out what a program must contain and who approves it.
How duely handles this
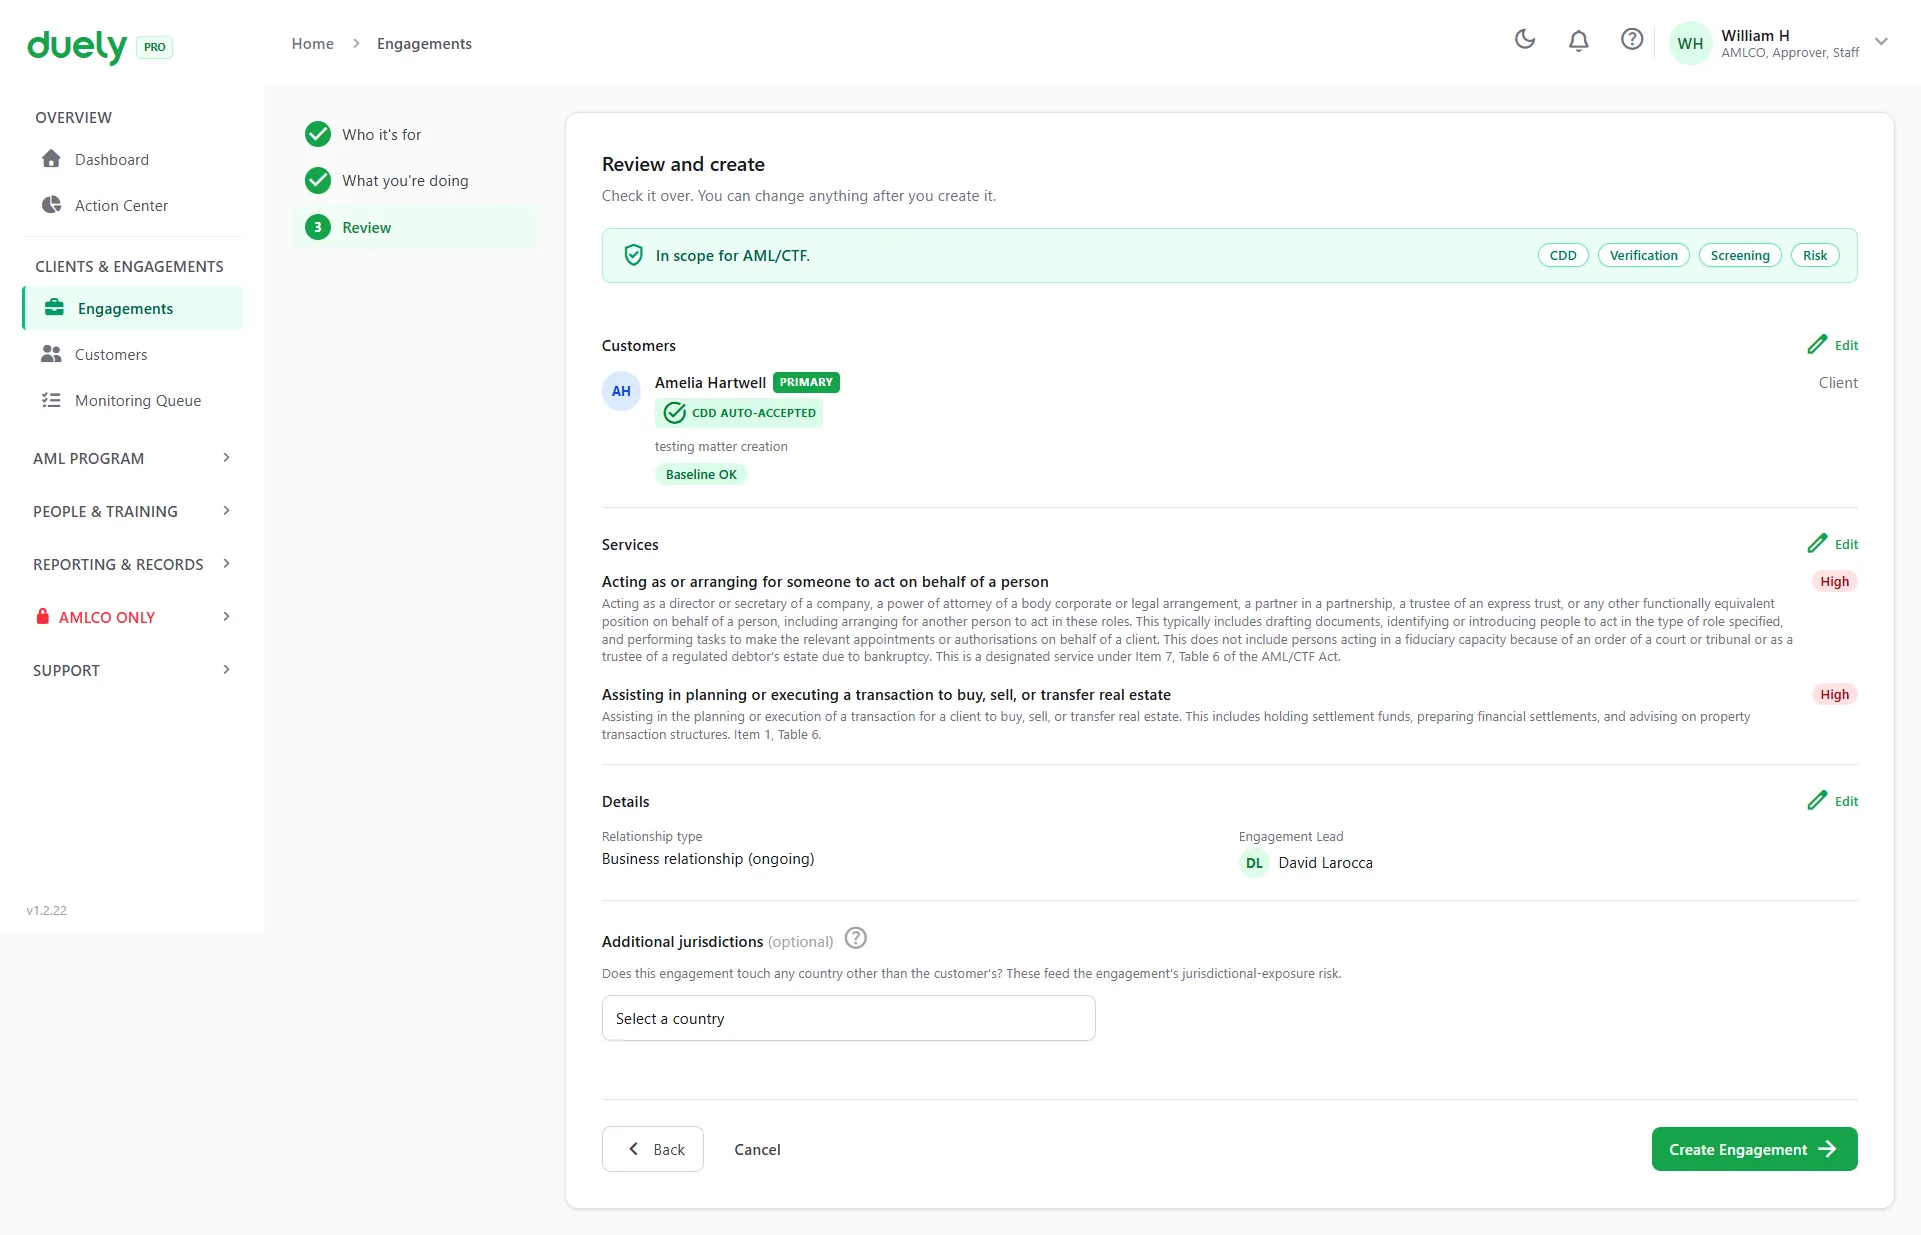
Whether a firm is captured is not a global setting in duely. Each engagement carries a scoping decision that records which designated service is being provided, and the obligations that follow attach to that decision. The service catalogue is per-vertical, so an accounting firm and a conveyancer see different lists, and a firm that provides a captured service occasionally is handled the same way as one that provides it daily.